

Kikoff - Build Credit Quickly

- 16.81K Reviews
- 4.8
- Downloads
- 5,000,000+
Our take on Kikoff - Build Credit Quickly from Appgk
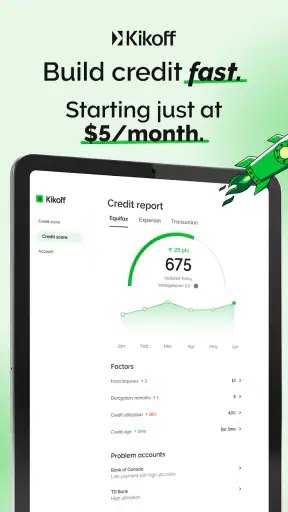
When I try a finance app that promises to help with credit, I pay attention to more than the first screen. I want to know what the app is actually asking me to do, where the important choices appear, and whether the experience feels understandable when money and personal information are involved. Kikoff - Build Credit Quickly, developed by Kikoff Inc., is aimed at people who want to start building credit without going through a traditional credit-card application. Its store summary makes the central appeal clear: no credit check is needed.
That positioning makes it interesting for someone who is new to credit, has a thin credit history, or would rather avoid another conventional card. It is a free finance app for everyone, and it has become a widely used option, with over five million installs. The public response is also strong: the app holds a 4.8 average from around 130 thousand ratings, alongside roughly 17 thousand written reviews. Those figures suggest that many people find the concept useful, but they do not remove the need to look carefully at how the product fits your own financial habits.
My overall impression is that Kikoff is best understood as a focused credit-building tool rather than a complete money-management center. It is not the kind of app I would open to plan a household budget, compare every borrowing option, or replace a bank account. Its value is narrower and, for the right user, more practical: it gives credit newcomers a way to approach credit-building without beginning with the usual credit-card routine.
How Kikoff earns trust before you commit
The first trust signal is the app’s straightforward target. Kikoff does not present itself as a general-purpose financial dashboard. The experience is centered on building credit, which makes it easier to judge whether it belongs in your financial toolkit. A narrowly defined purpose can be helpful because you are less likely to confuse a credit-building product with a full banking service.
Best Parts of Kikoff - Build Credit Quickly
Things to Keep in Mind About Kikoff - Build Credit Quickly
The developer is identified as Kikoff Inc., and the app has been available since March 25, 2021. Its current version is 1.181.3223, and it runs on Android 7.0 or later. These details matter less than the actual financial terms, but they help place the app in context: this is an established mobile product rather than something that appeared overnight.
I would still separate popularity from suitability. A high average rating tells me that many users had a positive enough experience to rate it well, but it does not answer the questions that matter most to an individual applicant. Before signing up, I would read every screen that explains the account, check what actions create an obligation, and make sure I understand how any payment or credit-building activity is supposed to work.
News and Features Related to Kikoff - Build Credit Quickly

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
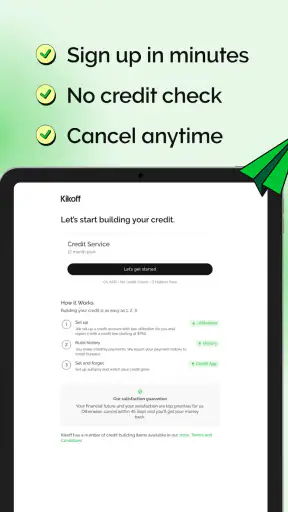
The phrase “no credit check needed” is especially important for people who are worried about being rejected. It may make the first step feel less intimidating, but it should not be interpreted as “no financial responsibility.” Any product connected to credit deserves the same care as a card or loan: understand the schedule, keep records, and do not activate something merely because the application feels easy.
What the app is, and what it is not
I see Kikoff as a possible starting point, not a universal answer. Someone with no established credit history may appreciate a product built around that exact problem. Someone who already has a well-managed credit card, a strong banking relationship, or several credit accounts may gain less from adding another service.
Don't want to read the full review?
This distinction is useful when comparing it with the usual alternatives. A traditional credit card can be more flexible because it may support everyday purchases, rewards, and broader payment options, but it can also tempt users to spend beyond their means. A secured card may offer a familiar card structure, though it commonly requires an upfront deposit. Kikoff’s appeal is the different entry point: it is designed to address credit-building without asking the user to begin with the standard credit-check experience.
That trade-off means I would not choose it simply because it is free to download. I would choose it only if the credit-building purpose matches my situation and if I am comfortable reviewing the account carefully. A free app can still connect you to financial commitments, and the download price says nothing by itself about every possible cost or condition associated with using a financial product.
Screenshots
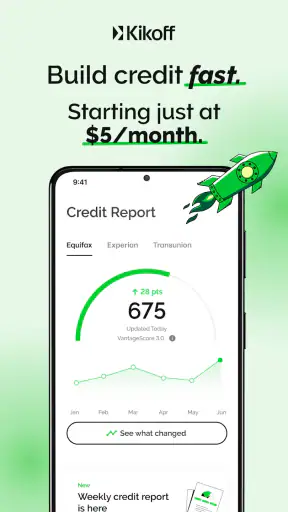
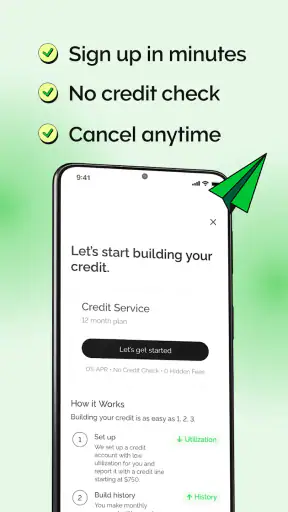
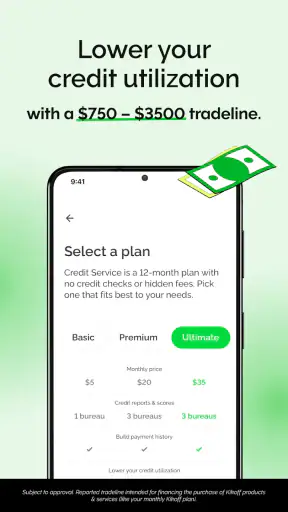
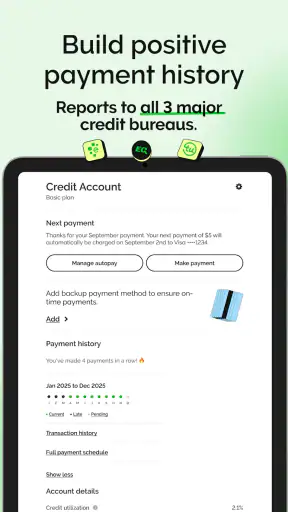
The controls I would check first
My preferred setup process for Kikoff would be deliberately slow. I would create the account, read the explanation of the product, and pause before accepting anything that affects payments or credit activity. The most valuable control is not a decorative setting; it is the ability to understand what I am agreeing to before moving forward.
I would also make sure the contact details on the account are current and that I can recognize every notification related to the service. Financial apps are easier to manage when account messages are not mixed with old email addresses or an inactive phone number. If the app presents reminders or account notices, I would treat them as part of the routine rather than ignoring them until there is a problem.
A practical tip is to keep a small personal record outside the app. I would note the date I enrolled, the product terms shown during setup, the payment method selected, and any confirmation messages. This is not because Kikoff is necessarily difficult to use; it is because a separate record gives me a clear reference if I later need to check when an action happened or compare a statement with my own notes.
I would also review the app after an update instead of assuming that every screen remains exactly where I remember it. The listed version is 1.181.3223, and mobile financial products can change their navigation over time. After updating, I would look again for account settings, payment information, support access, and any explanation of how the credit-building service works.
Where personal information deserves extra attention
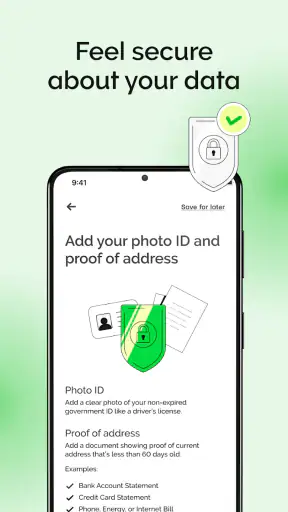
Any credit-related service involves a more sensitive sign-up than a casual shopping or entertainment app. I would expect to encounter identity, contact, and financial information during the process, so I would avoid starting registration on a public Wi-Fi network or on a device that other people regularly use. I would also lock my phone and avoid saving screenshots that expose account details.
My approach to permissions would be simple: allow only what is clearly necessary for the action I am taking, and read the explanation before approving access. If a permission request appears unrelated to account setup or account management, I would pause rather than tap through automatically. I would also revisit the phone’s permission controls later, because permissions granted during an initial rush are easy to forget.
The same caution applies to linked payment information. I would double-check the account or card details before confirming them, then watch the first scheduled activity closely. A useful workflow is to compare the app’s confirmation with the transaction shown by the bank or card provider. That extra check can catch a typing error early and helps me learn how quickly account activity appears on both sides.
I would not use a shared device for Kikoff unless I had a separate, protected profile and a reliable screen lock. Even when an app itself is secure, notifications, autofill, browser history, or an unlocked phone can expose sensitive information. Trust is partly about the service and partly about the environment in which I use it.
Keeping control instead of treating the app as automatic
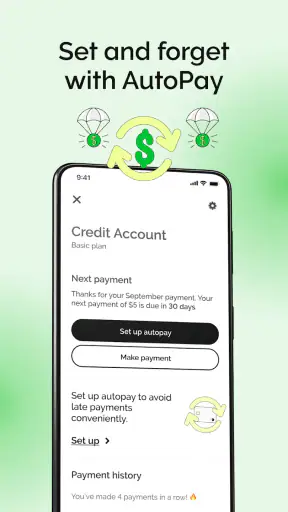
The biggest mistake would be to assume that enrolling means the credit-building work can be forgotten. I would put any relevant due dates or account checks on my normal calendar, not rely on memory or a single notification. I would open the app periodically, review activity, and confirm that the payment method still works.
This matters especially if a bank account is closed, a card expires, or a balance changes. An account that worked during registration may not remain suitable forever. I would update details promptly and keep enough money available for any activity I have agreed to. The app can make the process more accessible, but it cannot replace basic account supervision.
Another useful habit is to separate the goal from the temptation to open multiple products. If my goal is to establish a clean payment record, adding several services at once can make the picture harder to manage. I would give Kikoff a defined role, track that role for a while, and only then decide whether another credit product is genuinely necessary.
I would also be careful with the word “quickly” in the app’s name. Building credit is not something I would judge after a few days. Credit reporting, account history, and lender decisions depend on timing and broader circumstances. Kikoff may simplify the entry point, but it cannot guarantee a particular score or instant approval elsewhere. I would use it as a structured habit, not as a shortcut around responsible financial behavior.
A realistic everyday scenario
Imagine I have recently moved to the country, have little credit history, and want to prepare for a future apartment application. I do not want to apply for several cards, and I am concerned about being turned down. Kikoff could be useful as a focused first step because its stated approach does not require a credit check.
I would install the free app, read the account explanation carefully, and decide whether the product’s obligations fit my monthly budget. After setup, I would add the relevant dates to my calendar, keep the payment source funded, and inspect each confirmation. Once a month, I would review the account and keep copies of important records. I would not assume that using the app alone guarantees an apartment approval; I would treat it as one part of a longer credit-building plan.
Now consider a different user: someone who already carries a traditional card, pays it in full, and wants rewards or purchase flexibility. That person may find Kikoff too narrow. A regular card could better match the goal, provided the user can control spending and understands the risks of interest and missed payments. In that situation, adding a separate credit-building app may create more account administration without solving a real problem.
Small friction points that affect the experience
The no-credit-check approach reduces one obvious barrier, but it does not remove the need to read carefully. A user who wants a one-tap solution may be disappointed by the amount of attention financial setup requires. I consider that a reasonable friction rather than a flaw: when an app touches credit, a little deliberate reading is healthier than a fast, unclear enrollment.
The focused design can also feel limited if you expect one place to handle spending analysis, bill negotiation, savings goals, and credit education. Kikoff is not the app I would choose for a complete view of household finances. I would pair it with my bank’s own tools or a budgeting app if I needed broader visibility, while keeping the credit-building account separate and easy to monitor.
There is also a psychological limitation. Because the service is designed to make credit access feel less intimidating, some users may move forward too quickly. I would resist that feeling. “No credit check needed” can open a door, but I would still ask what I am receiving, what I must do each month, and how I can stop or change the service if my circumstances change.
Who should use it carefully, and who should skip it
I think Kikoff is worth considering for a credit beginner who wants a dedicated starting point, prefers a mobile workflow, and is willing to monitor account activity. It may also suit someone who has been hesitant to apply for a conventional card because of the credit-check process.
I would be more cautious if my income changes frequently, my payment accounts are often near zero, or I already struggle to keep track of recurring commitments. In that case, adding any credit-related service could increase stress. I would first stabilize my budget and create a reliable reminder system.
I would probably skip it if my main goal is rewards, everyday card spending, cash access, or full financial planning. A conventional card, secured card, bank tool, or budgeting service may be a better match depending on that goal. Kikoff makes the most sense when the goal is specifically credit-building and the user values an alternative to the usual application path.
My cautious verdict after weighing the trade-offs
Kikoff - Build Credit Quickly has a clear role and a clear audience. I like that its central promise addresses a real obstacle for people who are starting from little or no credit history, and the absence of a required credit check makes the first step less daunting. Its large install base and strong average rating show that the approach resonates with many users, although I would still make my decision based on the account terms and my own ability to manage them.
For me, the strongest reason to try it would be focus. I could use it as one controlled part of a credit-building routine, keep my records separately, review account activity, and avoid treating the app as a guarantee of a better financial future. The strongest reason to hesitate would be expecting it to replace a bank, a budget planner, or a flexible credit card.
My recommendation is cautious but positive: Kikoff is worth exploring if you need a dedicated credit-building entry point and can commit to reading every term and monitoring every payment-related detail. I would install it only on a protected device, review permissions and account controls, and give it a defined purpose. Used that way, it can be a practical option for a credit beginner; used as an automatic shortcut, it is much less convincing.
Kikoff - Build Credit Quickly FAQ
What is Kikoff - Build Credit Quickly, and how does it help build credit?
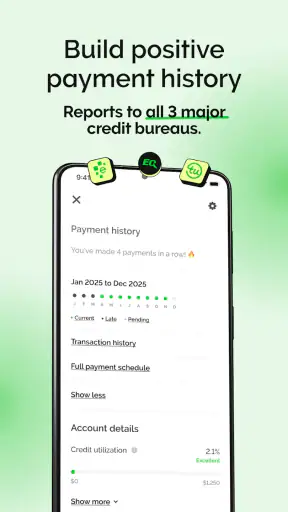
Kikoff is a credit-building app designed to help users establish or improve their credit history through eligible Kikoff products. Depending on the product available to you, your payments may be reported to one or more major credit bureaus. The app focuses on creating a manageable payment record, but approval, reporting, and results can vary by user and product.
Does Kikoff require a credit check or a security deposit?
Kikoff’s application process is generally designed for people with limited or damaged credit, and some products may not require a traditional hard credit inquiry. However, requirements can differ depending on the account or service you select. Users should review the current terms, possible fees, payment obligations, and any deposit requirements in the app before enrolling.
How quickly can Kikoff improve my credit score?
Kikoff cannot guarantee a specific credit-score increase or a particular timeline. Credit improvement usually depends on making payments on time, maintaining other accounts responsibly, and the information reported by the product to the credit bureaus. Some users may see changes after several reporting cycles, while others may need more time to build a meaningful credit history.
How much does Kikoff cost, and are there recurring fees?
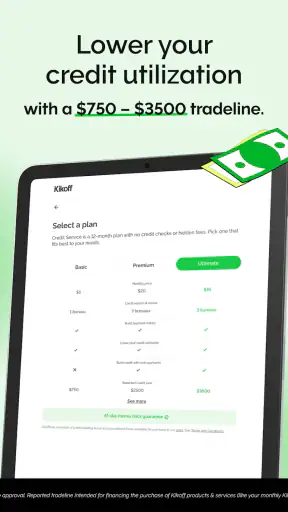
Kikoff offers different products and membership options, so pricing may vary. Certain features can involve monthly charges, annual costs, interest, or other fees, while some services may be advertised as low-cost or free under specific conditions. Before downloading or signing up, carefully check the latest pricing page, billing schedule, cancellation rules, and renewal terms.
Is Kikoff safe to use, and what should I know before signing up?
Kikoff uses account and identity information to provide its services, so users should review the company’s privacy policy and security practices before registering. The app may request personal and financial details for verification or account management. It is also important to remember that Kikoff is not a guaranteed credit repair solution, and missed payments or unpaid balances could negatively affect your finances or credit.












